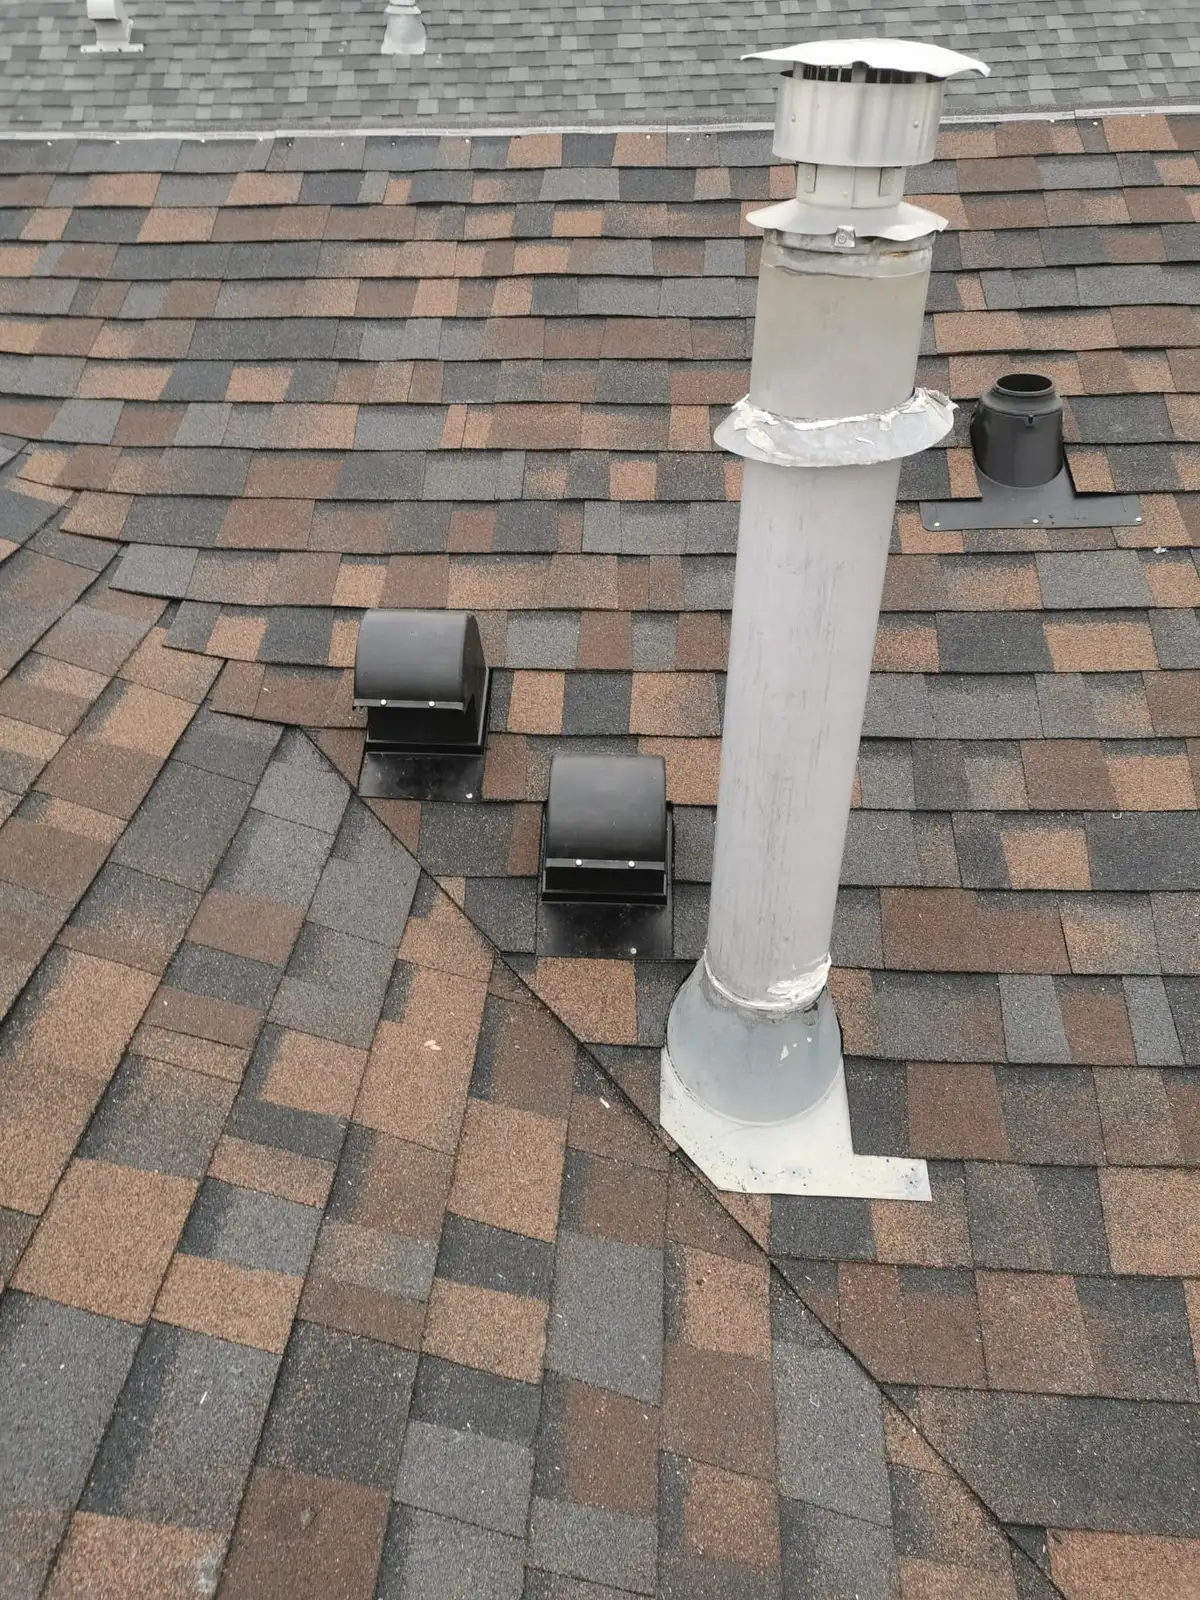
Home insurance and the shingle warranty cover different things. The Owens Corning, IKO, CertainTeed and Malarkey warranties all exclude hail, winds above the rated speed and acts of God, and cover only manufacturing defects. Storm damage goes to the insurer, documented with dated photographs of the shingles and of dented soft metals such as vents and gutters.
Quick facts
- Hail is excluded by all four. Owens Corning excludes “Acts of God, such as hail”; IKO excludes “hail”; CertainTeed excludes “hailstorm”; Malarkey excludes “hailstorms”.
- Wind limits. Owens Corning Duration 130 mph, 160 mph enhanced; IKO 177 km/h standard, 210 km/h high-wind application; CertainTeed 110 mph, 130 or 160 mph with upgrade; Malarkey 110 mph (177 kph), 130 mph (209 kph) enhanced.
- Wind warranty period. 15 years for the main laminated lines at all four; 5 years for IKO’s other shingles, CertainTeed XT 25 and Owens Corning Supreme.
- Claim clock. 30 days from discovery at Owens Corning, IKO, CertainTeed and Malarkey.
- Hail evidence. Indentations, fractures or circular bare spots on shingles, and dents on vents, gutters, siding, air conditioning units and other metal objects.
- Class 4 tests. UL 2218: a 2 in steel ball dropped from 20 ft, twice in the same spot; FM 4473: a 2 in ice ball fired at the panel.
- Age depreciation in the warranties. Owens Corning pays 72% of material cost in year 15; IKO’s example pays 20% of replacement shingles at 18 years; CertainTeed reduces 1/600 per month.
What does the manufacturer warranty cover that insurance does not?
Manufacturing defects, and nothing caused by weather. Owens Corning warrants that its shingles “are free from any manufacturing defects”; IKO covers “only for a manufacturing defect that significantly affects the water shedding performance”; CertainTeed warrants shingles “free from manufacturing defects”; Malarkey covers “manufacturing defects that adversely affect the performance of the shingle”. Each then lists what the weather does as an exclusion.
Each warranty has a non-prorated period followed by depreciation. Owens Corning’s TRU PROtection period is 10 years on Limited Lifetime shingles, after which compensation is 80%, reduced by 2% every year until year 40, then 20%.
IKO’s Iron Clad Protection runs 180 months on its Limited Lifetime shingles, and its worked example gives 20% of replacement shingle cost for a defect found at 216 months.
CertainTeed’s SureStart period is 10 years on Lifetime products, then a reduction of 1/600 per month, holding at 20% after year 40. Malarkey’s Right Start period is 10 to 20 years by product, then 1/480 or 1/600 per month, holding at 20%.
What they will not pay is as telling. IKO excludes “any damage to the interior or exterior of any building, or any property or contents”. Owens Corning is “not responsible for any incidental, consequential, special, punitive, or other damages of any kind, including damage to Purchaser’s structure or to Purchaser’s structure’s contents”.
CertainTeed excludes “any damage to the property, the building or its contents”. IKO and Malarkey pay nothing for tear-off or disposal; CertainTeed includes tear-off, metal work, flashing and disposal only for its Lifetime A products during SureStart. Water damage inside the house, the usual reason a homeowner calls, is never a warranty item.
The vents and underlayment on the roof carry warranties of their own, and they exclude storm damage in the same way. Owens Corning’s terms for its VentSure vents and RhinoRoof underlayments show the pattern.
| Owens Corning product | Warranty period | Excluded weather | What a valid defect claim pays |
|---|---|---|---|
| VentSure RidgeCat and RidgeProwler 30 rolled ridge vents, InFlow strip intake vent, strip heat and moisture exhaust vent | 20 years | Hail, strong storms, winds over the listed maximum, ice damming above leak barriers or flashings | Replacement product or the purchase price, no labour, reduced for each full year of use |
| VentSure Rigid Roll Ridge Vent | 50 years | Same | Same |
| VentSure Metal Slant Back Vents | 1 year | Same | Replacement product or the purchase price, no labour |
| RhinoRoof U20 synthetic underlayment | 20 years | Hail and strong storms | A contribution to repair or replacement, no labour |
| RhinoRoof U10 synthetic underlayment | 10 years | Same | Same |
| RhinoRoof Granulated and High-Temp self-adhered underlayments | 5 years | Same | Same |
None of these warranties transfers to a later owner, and each wants notice within 30 days of discovery. Owens Corning’s example for the vents: a 20-year product claimed in its 5th year pays 75% of its cost at the time of purchase.
Where three or more of Owens Corning’s five component categories are installed with its shingles, the components take the shingle warranty’s coverage period instead of these individual terms. A hail-dented vent or storm-torn underlayment is therefore a line on the insurance estimate, not a warranty claim.
Does home insurance cover roof leaks?
It depends on what caused the leak, and the warranties spell out which causes they hand back to the owner or the insurer.
Leaks from ice damming are excluded by all four: Owens Corning excludes “ice damming above the area covered by leak barriers or flashings”, IKO excludes “water infiltration arising from ice damming”, CertainTeed excludes damage “caused by ice backup or ice damming”, and Malarkey excludes damage “due to ice damming or water backup”.
Leaks through other components are excluded too: Owens Corning will not cover “metal work, counterflashing, failed and/or corroded roof nails, or pipe boots”, and Malarkey excludes “defects in, or failure of, flashing or metal work”. Every warranty excludes leaks that follow a storm as acts of God.
That leaves three routes. A leak traced to a shingle defect within the warranty period is a manufacturer claim, with the 30-day notice and sample requirements below.
A leak that follows hail or wind is an insurance question; whether a given policy covers sudden storm damage, and whether it treats a slow leak as wear or maintenance, is a policy term the owner must read and confirm with the insurer or broker.
The Insurance Bureau of Canada describes home insurance as cover for sudden and accidental damage, not for wear and tear or poor maintenance. A leak from a worn flashing, a blocked vent or an ice dam over an under-ventilated attic is usually the owner’s cost under both the warranty and the policy.
The guide to roof repair or replacement in Calgary covers whether that roof is worth patching. This guide describes the warranties; it is not legal or insurance advice.
What exactly do the warranties exclude for hail, wind and acts of nature?
Each warranty names hail, names a wind limit, and then sweeps in every other weather event. The exact wording matters when an adjuster or a manufacturer’s representative asks which coverage applies, so the table quotes it.
Exclusion wording, warranty by warranty
| Warranty | Hail | Wind | Acts of nature and other events |
|---|---|---|---|
| Owens Corning | ”Acts of God, such as hail" | "strong storms or winds (including gusts) over the maximum wind speed listed in the ‘Limited Lifetime Warranty Information Table’”; “No warranty shall apply for wind speeds or gusts in excess of the designated wind velocity" | "ice damming above the area covered by leak barriers or flashings, or snow or water infiltration through exhaust vents”; “objects (e.g., tree branches) falling on roof”; flooding “considered an Act of God” |
| IKO | ”hail”, within “acts of God or other causes beyond IKO’s control" | "gale or wind (except for the coverage in the Limited Wind Resistance Warranty)" | "lightning … hurricane, tornado, earthquake, explosion, flood, fungus contamination, solid objects falling on the roof, or any other causes”; “This exclusion does not apply to ordinary wear and tear of Shingles caused by the elements” |
| CertainTeed | ”Damage caused by lightning, hailstorm, earthquake, fire, explosion, flood or falling objects" | "Winds, including gusts, greater than the Wind Warranty MPH in Table 1" | "Damage caused by tornado, or hurricanes (other than as warranted under Wind Warranty MPH in Table 1)”; “ice backup or ice damming”; “impact, including such things as wind-blown objects, tools, equipment or foot traffic” |
| Malarkey | ”hailstorms" | "winds in excess of Wind Speed Limits (Table 1)" | "Violent or unusual weather conditions, such as flooding, hurricanes, tornadoes … or other force majeure events”; “Impact of foreign objects”; “Fire, acts of vandalism, and other, similar occurrences” |
Wind sits inside the warranty only up to a stated speed and only for a stated period.
Owens Corning covers blow-off “in winds (including gusts) up to the levels” in its table: 130 mph for Duration, Woodcrest and Woodmoor, 160 mph for Duration with the enhanced components, 110 or 130 mph for Oakridge with 4-nail or 6-nail application, and 60 mph for Supreme, for 15 years (5 for Supreme).
IKO covers blow-off for 15 years on Armourshake, Crowne Slate, Royal Estate, Dynasty, Nordic, Cambridge and RoofShake HW at 177 km/h, or 210 km/h with the high wind application, and for 5 years at 112 km/h on its other shingles.
CertainTeed covers 110 mph, or 130 or 160 mph where its starter and hip and ridge are used and the shingles are not applied over existing shingles, for 15 years on Lifetime products. Malarkey covers 110 mph (177 kph), or 130 mph (209 kph) with Smart Start and EZ-Ridge or RidgeFlex, for 15 years.
The four differ on shingles that blow off before the sealant strip has activated. Owens Corning and IKO accept no responsibility for blow-off before thermal sealing; Malarkey says failure to seal is not a defect but will hand-seal at its own expense if notified within the first year; CertainTeed “will furnish replacement shingles without charge” for blow-offs before cold-weather strips could reasonably activate, without labour.
Owens Corning also states how wind speed is proved: shingles are “conclusively deemed” exposed to excess wind if “the National Weather Service or other reputable weather agency records winds or gusts in excess of the designated wind velocity” in the municipality.
A valid wind claim is also capped. Owens Corning limits its maximum liability during the wind warranty period to the reasonable cost of hand sealing all of the shingles on the roof, and accepts no liability for damage to persons or property caused by blown-off shingles, or for blow-offs caused by damage to or failure of the roof deck.
Its warranty also excludes wind damage where installation, system configuration or site-specific conditions materially contributed to the loss, and wind damage on roof slopes outside its limits or on structures subject to abnormal wind amplification. Those losses are questions for the insurer or the installer, not the manufacturer.
Documenting hail damage for a claim
Photograph the shingles, photograph the soft metals, record the storm date, and have a professional inspect before any permanent repair. Hail damage shows as indentations, fractures, or multiple circular areas on the shingle where granules are missing.
A hailstone can break or weaken the bond between the granules and the asphalt, and the effect may not be apparent right away; it can take several months to show. When the shingle surface shows nothing yet, look for indentations on vents, gutters, siding, air conditioning units, heat pumps and other metal objects as telltale signs of hail impact.
Because hail falls in random patterns, a neighbour’s claim neither proves nor disproves yours. After a storm, Fratello Roofing & Exteriors Ltd inspects the roof, photographs the damage and provides the documentation your insurer needs for the claim.
The warranty claim rules double as a documentation standard for an insurance file. All four manufacturers want notice within 30 days of discovery. Owens Corning may ask for “pictures of Purchaser’s shingles or shingle samples” and warns that repairs made before its determination mean “the Purchaser’s claim may be denied”.
IKO wants “clear colour photos”, “two complete sample Shingles”, proof of purchase and access to the roof and attic. CertainTeed wants “proof of property ownership and the date of shingle purchase and application” and may take photographs and samples.
Malarkey requires claims “prior to any permanent repairs being made” and inspects first. Keep the same pack for the insurer: dated photographs of each slope, close-ups with a scale object, the soft-metal dents, the installation invoice, and the inspection report.
The report itself should come from someone with no stake in the outcome. A qualified roof inspector has no involvement in the specific roofing project except inspection, usually reports within a day, and issues a final report that certifies the work against the specification. A contractor’s estimate and an inspection report are different documents; your claim benefits from having both.
Both have a price. One 2026 inspection with a written photo report on a sloped house roof was billed at $800 before GST. On the estimate side, one 2025 hail-damage quote listed the Class 3 re-roof at $16,750 before GST, with new eavestrough and downspouts ($4,350) and fascia ($450) as separate lines.
Where Calgary-area quotes from 2025 and 2026 priced a Class 4 option beside Class 3 on the same roof, Class 4 added about $35 to $45 per square where the roof size was printed, and $500 to about $4,400 per house.
Where a storm has also flooded a property, Owens Corning treats flooding as an Act of God: submerged shingles are void of its warranty coverage, and such bundles are not suitable for sale and should be recycled.
Fire gets the same treatment. Owens Corning considers a nearby structure fire or a wildfire an Act of God and excludes any damage to roofing material from fire or excessive heat.
Asphalt shingles installed as part of a roofing system meet UL 790 Class A fire resistance, which means they retard flames and embers from burning through the roof into the attic, but they are not designed for temperatures above the normal maximum roof temperature, and heat above that level degrades their performance.
There is no way of knowing what temperature the shingles reached, so Owens Corning says damage cannot be determined without an inspection, and that a roof whose shingles are in any way distorted, singed, melted or blistered should be replaced. After a fire next door, that inspection report belongs in the insurance file.
Hail can take months to show on a shingle, so the dents in vents, gutters and other soft metal are the evidence to photograph first, before any permanent repair. What the claim then pays is a policy matter.
Replacement cost, actual cash value and the warranty’s own depreciation
Replacement cost settles a claim at what it costs to replace the roof today; actual cash value deducts depreciation for the roof’s age and condition first. Which basis a policy uses, and the roof-age schedule it applies, is set by the insurer and written into the policy and its endorsements.
The Insurance Bureau of Canada notes that some Alberta policies carry an endorsement limiting roof and siding claims to actual cash value, so ask your insurer or broker which basis applies and at what roof age it changes.
The deductible, including any separate hail or wind deductible, is also a policy term. The Insurance Bureau of Canada notes that a hail deductible, where one applies, is typically higher than the usual home insurance deductible, so confirm both amounts with your insurer or broker.
The warranties show how an age-based schedule works. Owens Corning pays 100% of covered cost for years 1 to 10, then 80% reduced by 2% every year until year 40, so a defect claim in year 15 pays 72% of material cost and no labour, and one in year 20 pays about 62%.
IKO’s example: shingles installed in October 2024 with a defect found in October 2042, 216 months later, are reduced by 384/480, so IKO’s “maximum obligation would be 20% (100-80) of the cost of the replacement Shingles”.
CertainTeed subtracts 1/600 of the replacement shingle cost per month after SureStart, so a 20-year-old Lifetime roof is at 60% for material only. Malarkey Legacy depreciates at 1/600 per month after its 20-year Right Start period and holds at 20% after year 40.
A 20-year-old roof is therefore partly covered for material under every warranty and never for labour; what the insurer pays for storm damage on the same roof is the policy question above.
Policy checks before hail season
Read the settlement basis, the roof-age schedule, the deductibles and the impact-resistance discount before June, when Calgary’s hail season begins.
Each is a policy term to confirm with your insurer or broker: whether roof claims settle at replacement cost or actual cash value and at what roof age that changes; the standard deductible and any separate hail or wind deductible; and whether the insurer discounts UL 2218 Class 4 or FM 4473 Class 4 roofs and what proof it needs.
Manufacturers say only that a Class 4 rating may qualify for a homeowner insurance discount and that homeowners should check with their insurance company. The page about roofing built to resist Calgary hail covers the Class 4 products themselves.
Then check the warranty side. Confirm the installation date and keep the invoice, because every manufacturer counts from installation and asks for proof of purchase.
Confirm the wind warranty components were installed: CertainTeed’s 130 or 160 mph upgrade requires its starter and hip and ridge and no roof-over, Owens Corning’s 160 mph requires its components and starter on eaves and rakes, Malarkey’s 130 mph requires Smart Start and EZ-Ridge or RidgeFlex, and IKO’s 210 km/h requires extra nails, manual sealing and IKO starter.
If the house changed hands, confirm the transfer was filed: Owens Corning within 60 days, IKO within 30 days, Malarkey within 60 days, CertainTeed once only.
And know the class on the roof: Owens Corning rates Duration FLEX and Duration STORM at UL 2218 and FM 4473 Class 4 and the rest of the Duration series at Class 3, with ImpactRidge caps required to complete a Class 4 system.
What this means for a Calgary roof
The August 2024 Calgary hailstorm was among the costliest insured events in Canadian history, and every shingle warranty compared here would have excluded it.
In Calgary the warranty protects against a defective shingle; the policy protects against June to August hail and Chinook gusts, and only to the terms you have confirmed before the storm. Fratello Roofing & Exteriors Ltd can inspect and photograph storm damage, write the condition report and quote the repair or replacement; call (403) 404-9833.
Questions people ask
Does home insurance cover roof leaks?
Only as the policy defines it; the shingle warranties are not insurance policies. They show that leaks from ice damming, flashings, nails and storms are not warranty items, which is why the leak’s cause decides whether the owner, the manufacturer or the insurer pays.
Will insurance cover a 20-year-old roof?
That is a policy term to confirm with the insurer. The warranties show the shape of age-based settlement: at 20 years Owens Corning pays about 62% of material, CertainTeed 60%, IKO’s example 20% at 18 years, and none pays labour.
What is the difference between replacement cost and actual cash value?
Replacement cost pays today’s cost to replace the roof; actual cash value deducts depreciation for age and condition first. Which one a policy applies, and when it switches, is the insurer’s term to confirm.
How do I document hail damage for a claim?
Dated photographs of each slope and of dents on vents, gutters, siding and air conditioning units, the installation invoice, an independent inspection report, and no permanent repairs before inspection. Bare spots can take months to appear, so a follow-up visit matters.
What should I check in my policy before hail season?
Settlement basis, roof-age schedule, hail and wind deductibles, and any Class 4 discount, plus the warranty’s installation date, component list and transfer filing.